
Quarterly Report, Q3 2026: Cyber Security Vendor M&A and Funding News
Published by Pinpoint Search Group — the cybersecurity executive search firm that tracks every disclosed vendor funding round and acquisition in the sector.
At a glance
Get the full Q3 2026 dataset — every named company, round, investor, segment, and acquisition.
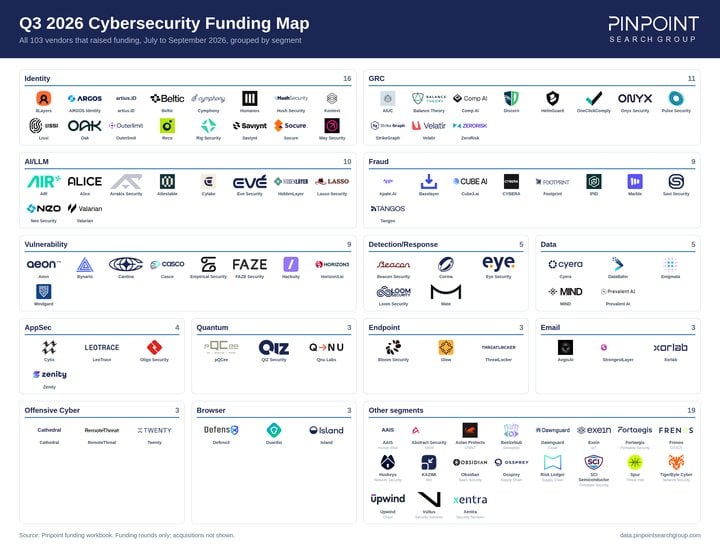 Q3 2026 Funding MapSee all 103 companies that raised in Q3 2026, grouped by segment →
Highlights and Analysis
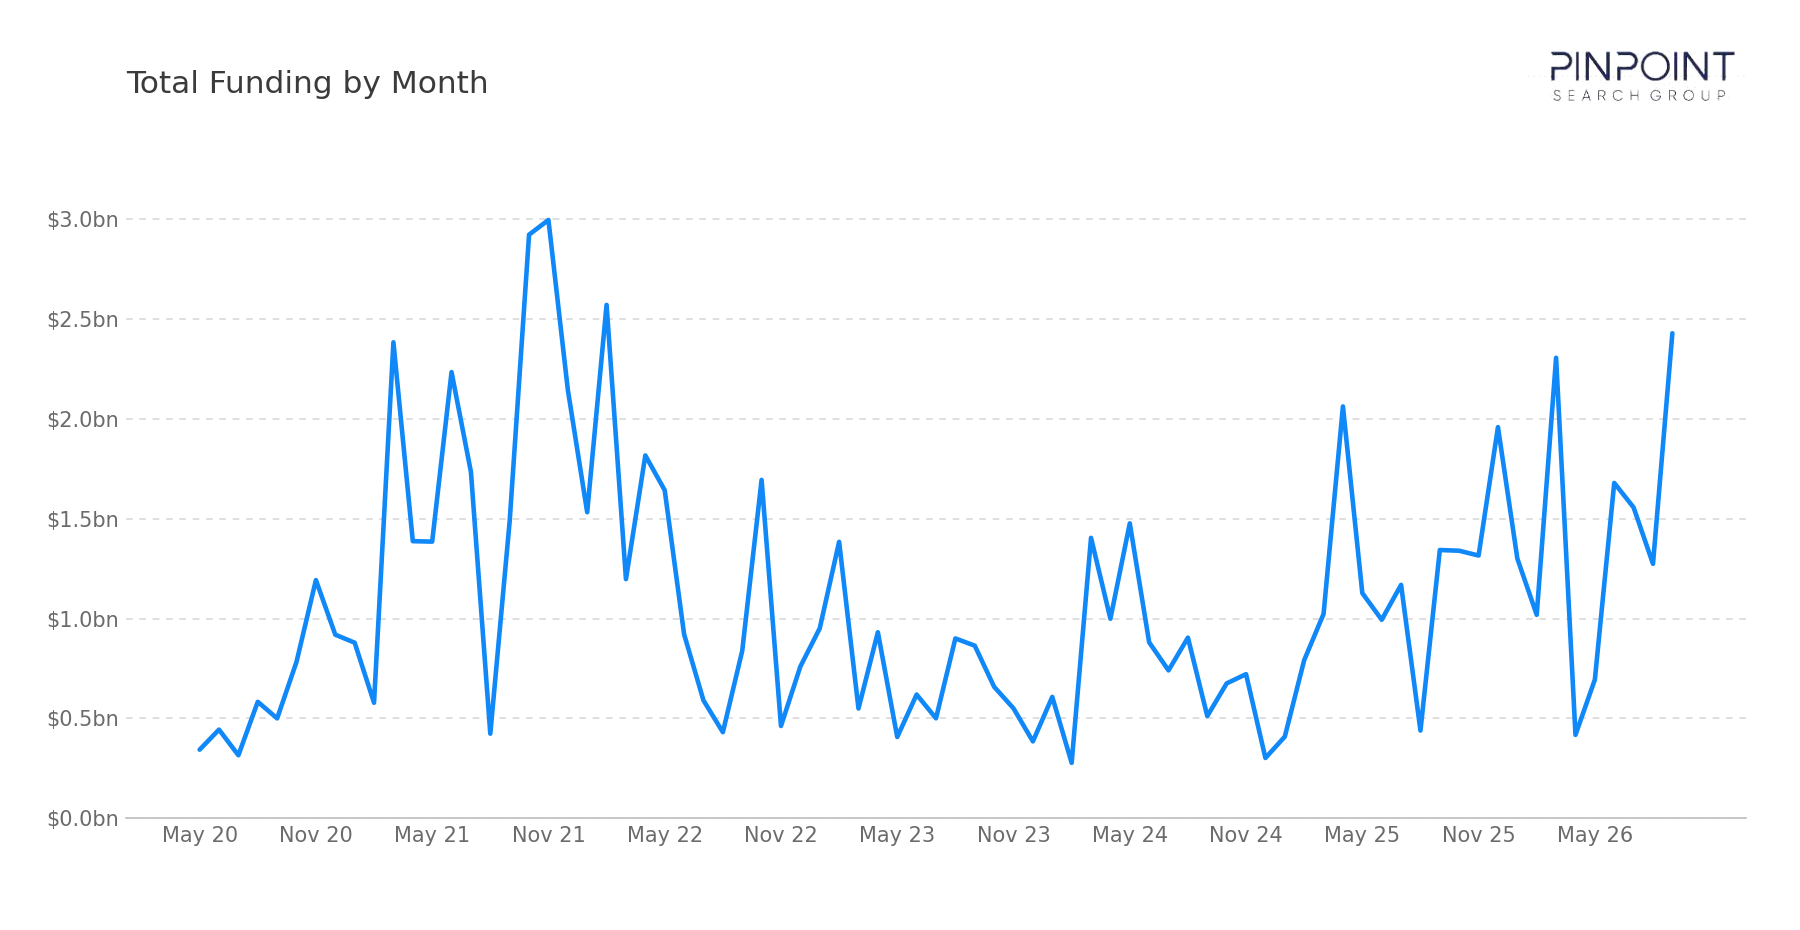
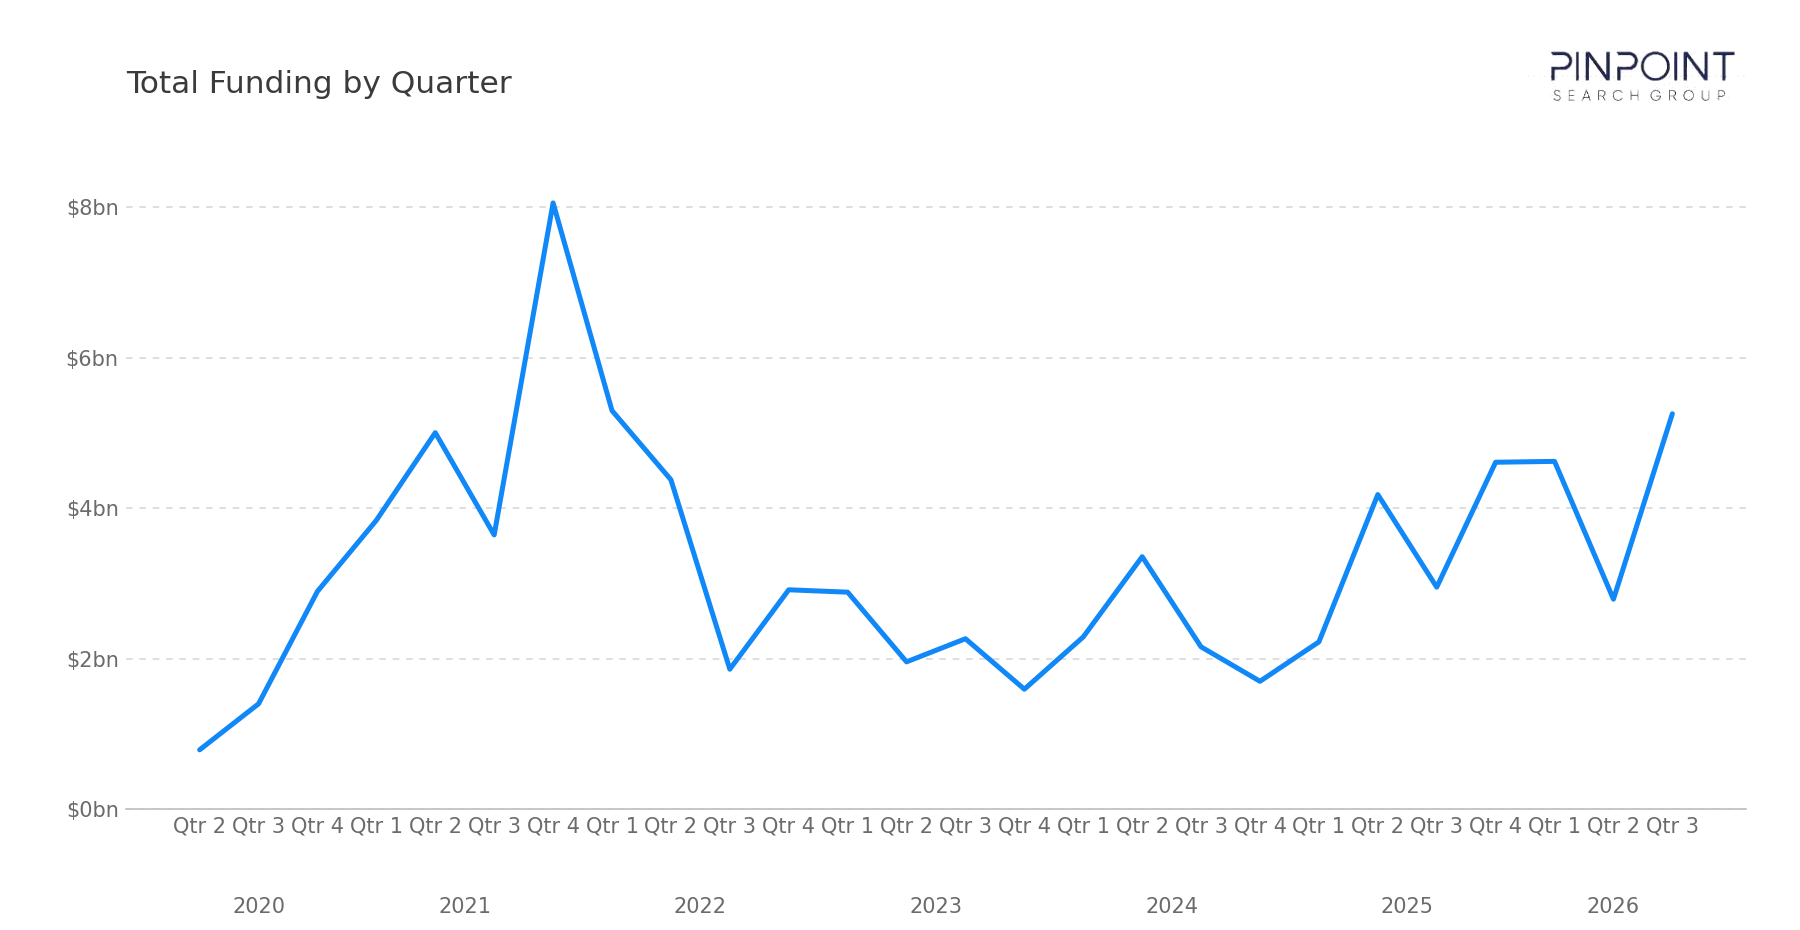
In Q3 2026, our team tracked 153 transactions, including 104 funding rounds and 49 acquisitions and mergers. Disclosed funding reached $5.26B, the most in a quarter since Q1 2022. That's up 78% compared to Q3 2025 ($2.95B) and nearly double Q2 2026 ($2.79B).
September recorded 70 transactions, including 46 funding rounds and 24 acquisitions. The $2.43B raised was the most in a month since February 2022.
Year to date, $12.7B has been raised, the most through September of any year since we started tracking in May 2020, just ahead of 2021's $12.6B.
Acquisitions stayed busy, with 49 deals in the quarter after 54 in Q2, and 134 tracked through September.
Funding Overview
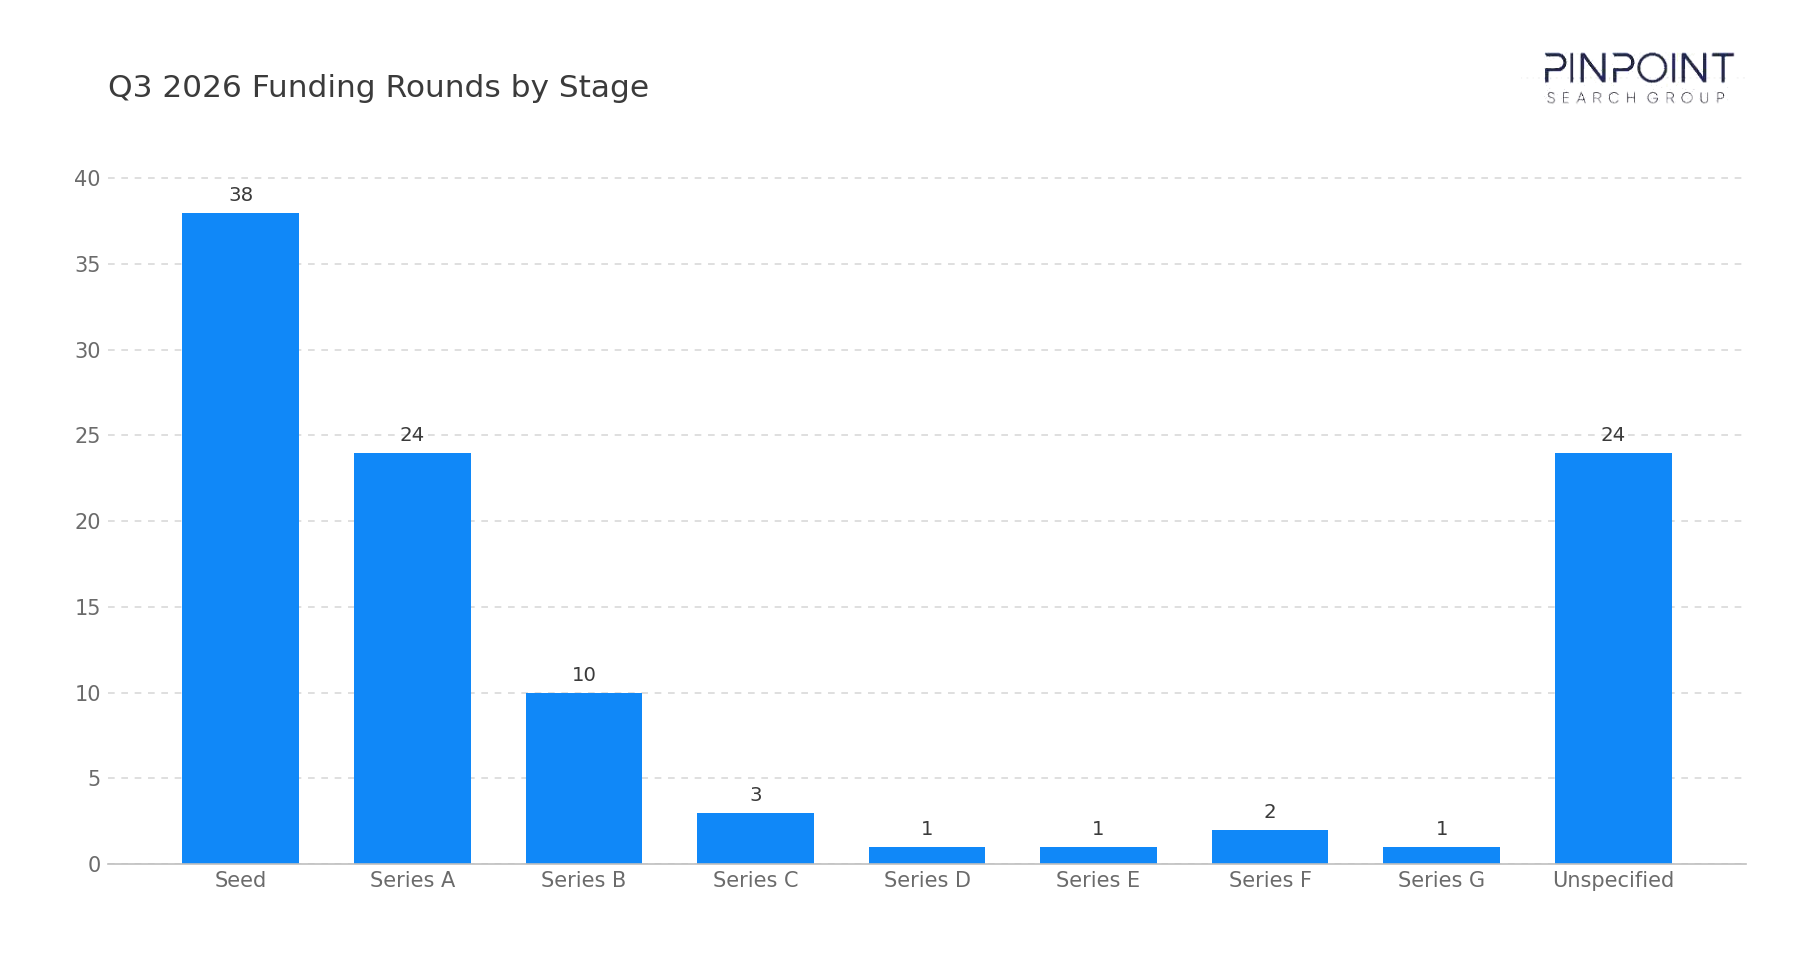
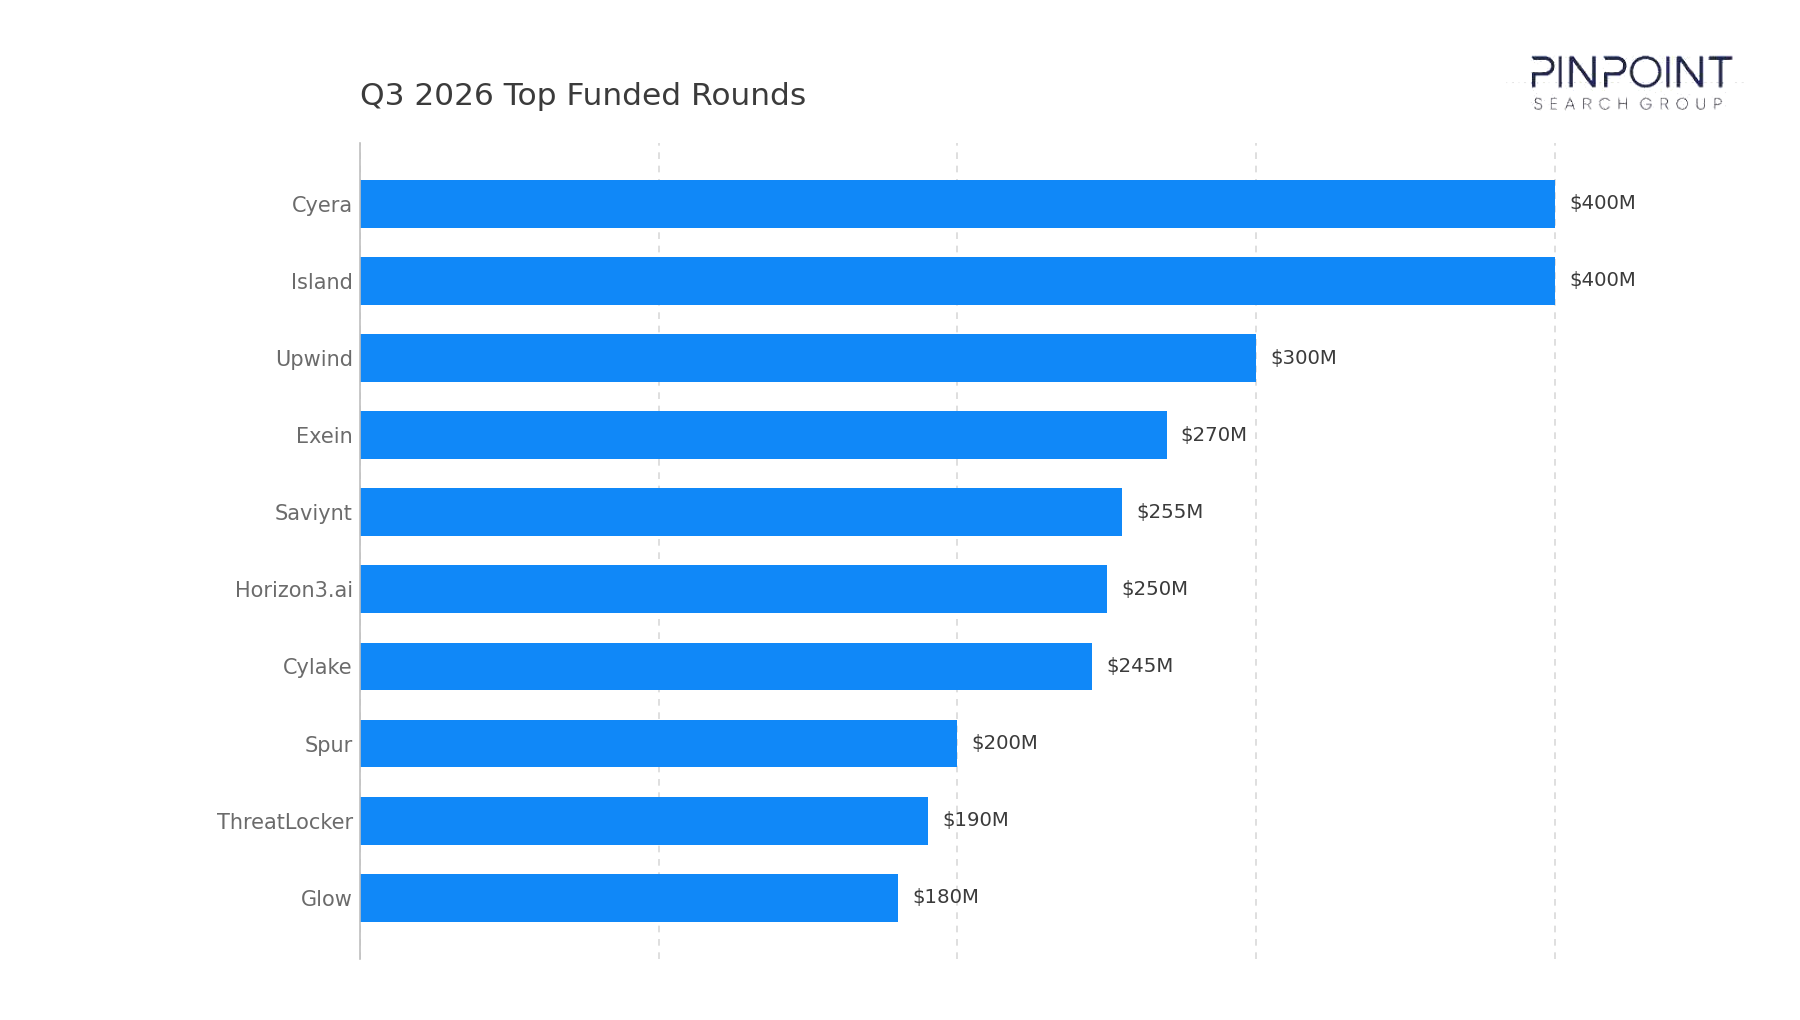
Seventeen rounds reached $100M or more, the second-highest quarterly count since we started tracking in May 2020, behind 20 in Q4 2021. Cyera and Island led at $400M each, followed by Upwind at $300M. Five rounds were Series D or later, including ThreatLocker's Series F and Horizon3.ai's Series E. Together the $100M+ rounds account for 68% of the quarter's disclosed capital. Seed and Series A made up 62 of the 104 rounds (60%) and $1.16B of the capital (22%).
By transaction count, the quarter's most active segments were:
- Identity, at 23 transactions: 16 funding rounds, including Saviynt and Socure, and 7 acquisitions, including Cyera's purchase of Oasis Security
- Security services, at 15 transactions, 13 of them acquisitions
- AI/LLM security, at 13 transactions, with rounds for Cylake and HiddenLayer, plus Fortinet's acquisition of Virtue AI
- Fraud, at 13 transactions, 10 of them funding rounds, alongside Visa's acquisition of BioCatch
- Governance, risk, and compliance, at 13 transactions, almost all funding, led by Onyx Security's $113M Series B
A note on segments. Cybersecurity is changing quickly, and our segment labels need to keep pace. For deals added since September 23, 2026, we retired several overlapping labels and folded them into broader ones. The most visible change is Human Risk, which replaces Training and Social Engineering and covers vendors focused on the people side of security. Earlier reports and historical data keep their original labels.
Market & Macro Signals
Large rounds returned in number. The 17 rounds of $100M or more were up from 7 in Q2 and 11 in Q1. Many went to companies we have tracked for years: Cyera raised its eighth round in our data, and Island and ThreatLocker each raised at least their fourth.
Financial firms bought security companies. Visa acquired fraud prevention vendor BioCatch, Munich Re acquired cyber insurer At-Bay, and Bank of America acquired testing firm MDSec.
Security services consolidated. Thirteen of the 49 acquisitions and mergers involved services firms, ten of them in September. A-LIGN bought Pathfynder and AssurePoint, CyberMaxx acquired Avertium, and NetSPI merged with Synack.
M&A Activity & Strategic Movement
Eight of the quarter's acquisitions disclosed a price, totaling $4.34B, the largest being Visa's $2.4B for BioCatch and Cyera's $1B for Oasis Security.
Detection and response drew several buyers. Cribl bought CardinalOps in July and Radiant Security in August, and CrowdStrike bought XM Cyber. Elsewhere, security vendors added to their offerings: Keyfactor bought Cofide in identity, and Jamf bought browser-security vendor Keep Aware.
Cyera, Socure, and Upwind each raised and bought in the same quarter. Cyera paired its $400M round with the Oasis acquisition, Socure raised $156M and bought Fravity, and Upwind raised $300M and bought AI-security startup Aegis.
Looking Ahead
We expect these trends to continue into Q4:
- More buyers from outside security, particularly financial firms adding fraud, identity, and insurance capability
- Continued consolidation among security services firms
- Large rounds going mostly to vendors that have raised before
The full Q3 2026 dataset — every named company, round, investor, segment, and acquisition — is in the data feed. Get the full Q3 2026 dataset →
Methodology
Every transaction in this brief was sourced from a primary public report and dedupe-checked against the master Pinpoint funding workbook, which now contains roughly 2,800 transactions back to May 2020. Funding totals reflect disclosed capital only; acquisition values are included where publicly available.
Each deal is classified against Pinpoint's normalized cybersecurity segment taxonomy — read directly off what the company says they protect and mapped to one of the canonical segments. The taxonomy has been maintained continuously since 2020 and is adjusted as the market changes. Identity, Data, Detection / Response, and Threat Intel have been tracked from the first month of the series; AppSec and GRC entered the following month; emergent categories (AI/LLM, Supply Chain, Quantum) are added when they first appear in vendor positioning. That normalization layer is what makes multi-year, cross-segment comparisons possible against an otherwise inconsistent vocabulary in the broader market.
About Pinpoint Search Group
Cybersecurity innovators work with Pinpoint Search Group to identify, attract, and land professionals that enable maturation, scale, and successful outcomes. As start-ups continue raising millions in funding and established vendors make acquisitions to round out their offerings, Pinpoint Search Group is keeping track.